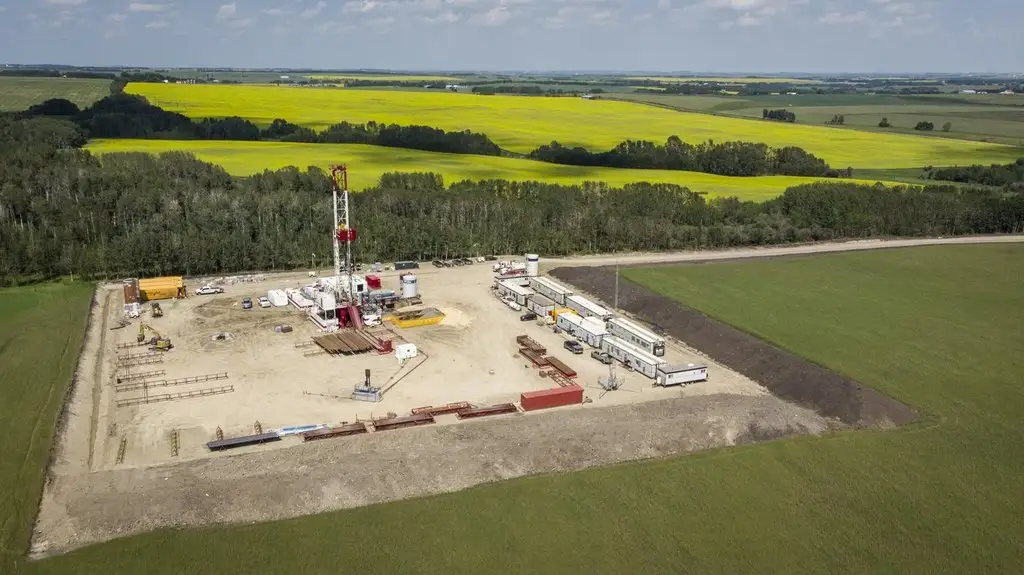
Canadian Natural Resources Ltd. is making a bold move to strengthen its grip on northwestern Alberta's energy landscape, agreeing to acquire Advantage Energy Ltd. in an all-cash transaction valued at $2.53 billion including debt.
The blockbuster deal—valued at $13.55 per Advantage share—gives CNRL immediate access to roughly 79,000 barrels of oil equivalent daily production capacity, plus significant undeveloped reserves in the Montney and Charlie Lake regions near Grande Prairie. It's the kind of strategic consolidation that industry watchers have come to expect from the Calgary-headquartered energy heavyweight.
A Strategic Fit for Area Growth
CNRL president Scott Stauth framed the acquisition as a natural extension of the company's existing footprint. "Advantage Energy is an excellent strategic fit for Canadian Natural," Stauth said in a statement Monday. "The acquisition builds on our significant Montney and Charlie Lake positions and provides additional synergies of scale to further improve on area efficiencies."
That emphasis on operational synergies reflects CNRL's proven playbook: buy quality assets in clusters where it already operates, then extract value through lower costs and tighter coordination. The company has successfully used this strategy for years, and Advantage Energy—with its established infrastructure, deep drilling inventory, and reputation for cost discipline—appears to be precisely the type of property that fits the mold.
Advantage Shareholders Get Immediate Value
Advantage Energy's board, led by interim CEO and board chair John Festival, concluded that selling to CNRL was the best way to deliver value to shareholders after a comprehensive strategic review.
"Advantage has built a premier business over the last 25 years, with top-tier well performance, significant owned and operated infrastructure, a deep drilling inventory in the Montney and Charlie Lake, and a relentless cost focus," Festival said. "Following an extensive review of our strategic alternatives, the board concluded that this transaction is the best path to crystallize the value we have created."
Festival's language signals confidence that the company extracted maximum value—a premium to shareholders that reflects Advantage's operational strength and strategic location.
Analysts Question the Price Tag
Not everyone thinks CNRL paid a bargain. Desjardins Securities analyst Robert Mann noted Monday that the Calgary company appears to be paying full price for Advantage, which runs counter to CNRL's traditional strategy of acquiring assets during market downturns when valuations soften.
"However, the rationale is consistent with (Canadian Natural's) strategy of consolidating assets where it can drive area efficiencies, particularly after reaching its net debt target," Mann wrote in a research note. "Importantly, management reiterated that its target of returning 100 per cent of free cash flow through share repurchases remains intact despite the transaction."
That last point matters: CNRL is signalling it won't sacrifice shareholder returns even while deploying billions for growth.
Regulatory Hurdles Ahead
The deal requires approval from Advantage Energy shareholders and regulatory authorities, with an expected close in the first quarter of 2027. Mann flagged the Competition Act review as the critical milestone to monitor, given recent delays on some of CNRL's other acquisitions. Those regulatory checkpoints could add uncertainty to the timeline, though CNRL's size and track record suggest approval is likely.
For Alberta's energy sector, the Advantage-CNRL tie-up represents another consolidation move in an industry increasingly dominated by larger players capable of absorbing significant capital outlays and weathering volatile commodity markets.
This article is based on reporting from Global Calgary.